GST Impact ? Transportation is associated with shifting of goods, passengers, etc from one place to another using different modes like roadways, railways, airways or through water. Transportation is an activity which connects different business with suppliers and customers. Transportation has an major impact on Indian economy.
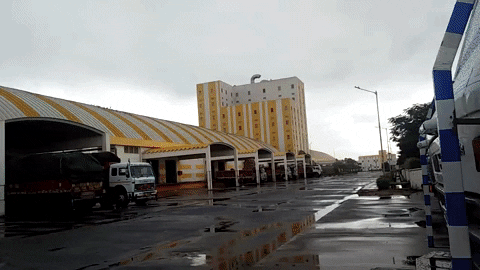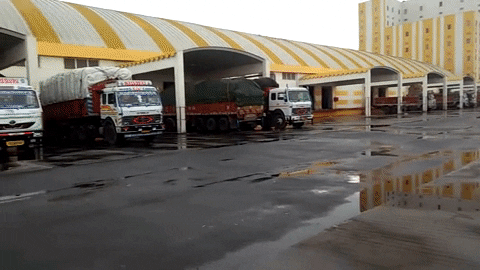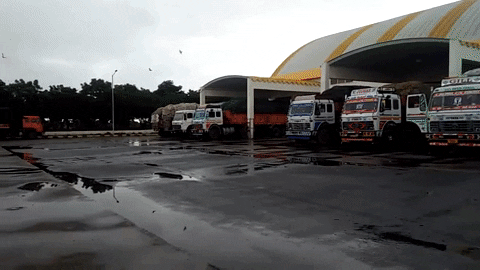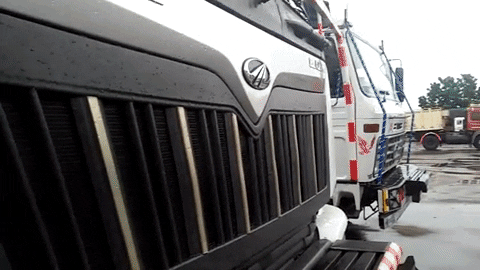
After GST was introduced it had an positive impact in the transport sector. It has helped to ease the movement of consignment, goods via roads, rails, air and sea. 20% increase in transport efficiency was noted due to the dismantling of various checkpoints. The e-way bill has also helped drivers as it reduced the burden of enduring the procedures at various checkpoints.
The Planned GST system has replaced several state and federal tariffs for a single tax. Previous complicated tax structure in India referred that logistics decision, choice of setting up warehouses and distribution center , were taken on the basis of tax regime which included central sales tax and state value added tax rates.
GST unleashed an new era of developing logistics infrastructure, taking investments to new level and transportation. Transport vehicles used to waste about five to seven hours daily at interstate checkpoints. As per the estimation by World Bank, simply having delays due to roadblocks, tolls and other stoppages could cut freight times by 20% – 30% and cost logistics by 30% – 40%.
Impact of gst on Indian economy :–
As per the GST Law 2017, services by way of transportation of goods by road is not kept under GST so no GST tax is payable on it. GST will only payable on services of Goods Transportation Agency ( GTA ).
Goods Transportation Companies :-
GTA is any person of firm who is providing service in relation to transport of goods by road and issues ‘Consignment Notes’. If the service provider does not provide consignment note the transport of goods by road won’t be taxable. Services of GTA in transporting goods will account for GST at 5% or 12%. In 5% GST you cannot take the credit of input tax charged on goods or services. Any service provided by GTA to an unregistered person including an ‘unregistered casual taxable person’ will be considered Nil except following recipients :
The following are considered to be service recipients :-
- Factories registered under Factories Act, 1948
- Society Registered under Society Registration Act, 1860
- Person registered under CGST Act, SGST Act, IGST Act, or UTGST Act
- Established Corporate Body
- Any registered or unregistered partnership firm
Government has also kept some GTA Services out of the GST Act. Below is the list of some such services : –
- Agricultural Produce
- Flour, pulses, rice ,milk, salt and other food grains
- Organic Manure
- Registered Newspapers or Magazines
- Relief materials going for victims of natural or man-made disasters
- Defence Equipment’s
Rates of GST on Different Modes of Transportation India :–
Roadways GST Rate :- (surface road transportation service)
Road transportation goods are subjected to 5% or 12% GST tax with credit availability to input tax.
Airways GST Rate :- (Aviation Industry GST)
Good transport is taxed at 18% for within India and out of India with credit availability to input tax.
Railways GST Rate :- (Rail Train Transportation Industry)
Goods transportation through Indian Railways are subjected to 5% tax with credit availability and this makes a strong competition between road and rail transport. For transportation of goods other than Indian Railways tax is charged at 12% with credit availability.
Waterways GST Rate :- (Water Transportation Industry)
Waterways transportation is charged at 5% with credit availability.
Benefits of GST on Indian Goods Transport Services :–
Simplified Tax :-
The implementation of GST removed various taxes and tariffs of each state. This reduced the complexity which was faced in transportation of goods before GST. Before transporters had to pay different tax in every state. All these tax rates were different. GST brought out “ONE TAX ONE SOLUTION” system.
Reduction Warehouse cost :-
The previous tax system used to collect higher logistics cost. It was reduced to about 20% after the implementation of GST. As each state used to have different tax rates, companies used to own warehouses in each state instead of at one place which also increased warehouses costs. After implementation of GST companies don’t need to get warehouses in different state and this improved logistics.
Increase Efficiency :-
One tax one solution has made transportation seamless throughout the country with the removal of multiple checkpoints, entry permits, extra paper works, etc. After GST all the complexities in transport sector in various states are removed. These saves transportation time, operating costs and efficient logistics.
Driven By Technology :-
GST has entail a new set of compliance requirements and to fulfil this companies will require to adopt new ERP accounting systems and stock management systems. The industry is now able to avail tax credits for all its good, goods vehicles, delivery vans or packing machinery. The introduction of e-way bill has helped the firms in the industry to sort out the confusion by maintaining uniformity in the industry.
Reduced Paperwork and Consolidation :-
Under GST lot of taxes like entry tax, OCTROI has been removed. Removal of this kind of taxes had ease the paperwork procedure for the logistics service providers.
Disadvantages of GST :-
- Some experts says that GST is nothing new but it is just a new name given to the previous tax system.
- The service tax was 15% previously but now it has become 18%. Due to this many services have become costlier with telecom, airline, and banking affected mainly.
- This new GST Act has given the control of business to state and central governments. The business owners are now more confused about the system as they are facing issues to understand the rules identified.
- After implementing GST government collected a large amount of money through taxes in its first few instances. Businesses had to let go large amount of tax . Several businessmen complained about not getting the credit of input tax. Officials found some mismatch of data and they denied the credit of input tax to many. As a result many had chaos with the officials and are not happy with the GST.
- This GST Act had not been so fair with the disabled people. Many things that were tax free earlier for disabled people had now been included under GST tax. Before implementation of GST brail paper, hearing aid and motorized wheelchair were tax free but now this things are also being taxed.
- Government has not spared banking systems also. At one side they are trying to give push to banking services and insurance in India and on other side government taxed banking and insurance services at higher rates when compared to previous rates.
- Implementation of GST also had an negative impact on discount and rewards program. Before GST product was taxed on post-discount rates but now the products are taxed on pre-discount rates. Many companies have suspended their rewards program.
- As the government chose the mid year for launch of GST this lead to problems in taxation and reporting during the end of the financial year. For good reason government should have launched GST at the end of the financial year it would have avoided the confusion during taxation and reporting.
- As per the GST rules sellers need to get registered in every state he is doing business and this has increased more burden and complexity for seller. The government should have thought of a centralised registration procedure to ease the work sellers during the rollout.
- GST offered return tax benefits to other business but only transport sector has been kept deprived of it. Though transport sector plays an important role in the economy of country it has been kept away from return tax benefit.
- Most of the check posts were deactivated after the implementation of GST. Before GST transport vehicles were checked at every check posts. This was time consuming and also the officials at check posts used to harass drivers and fine money for no valid reason. After deactivating check posts there was decrease in corruption, transportation cost and time. But now this check posts have started again and the situation have become as it was before.
- Complexities in the structure and implementation GST is preventing local firms from investing in the market. Also government gives more free environment to the foreign investors in tax and rules. These partiality with our own business sectors is not at all valid.
Conclusion :-
Government is keeping more trust on the foreign investors while ignoring small and local investors. If government shows a firm belief in local investors India could achieved heights. That’s the difference between India and China. China firmly linked its business sector with country and now we can see its result. China is among the fastest growing economy and they are doing well with their own made products in the entire world. In India every state, every region, every politicians keeps their own profit ahead and works according to that. If this continues in India, India will soon see its worst phase.
No doubt many sectors have been doing good after implementation of GST but still there needs some improvement in implementing GST. Partiality between local and foreign investors should be vanished. Rules should be same for every businessmen and then only we can see a fair competition.
Click and follow for regular warehousing Upgraded Updated news report :- Please Click
Recommended :-
- Please click and See Our Endless Journey – Please Click
- Manufacturer association in India – AIAI India ( www.aiaiindia.com )
- Merchants manufacturer industries manufacturing companies
- Difference between sales and marketing
- Fraud Cases and Examples in Business
- Business Problems and Solutions
Public frequently asked questions (FAQs) :-
🇮🇳 GST Impact on Indian Economy 2026: Benefits, Disadvantages, Tax Reforms and Effects on Transport & Logistics
🚛 How Goods and Services Tax Changed India’s Economy, Businesses, Consumers and Freight Transportation
India’s Goods and Services Tax (GST) is one of the most significant indirect tax reforms in the country’s economic history.
Introduced on 1 July 2017, GST replaced a complicated system of central and state indirect taxes with a more integrated framework.
The reform changed how businesses calculate taxes, purchase goods, manage warehouses, transport cargo and maintain financial records.
For ordinary consumers, GST influences the prices of many products and services.
For manufacturers, it affects procurement, production costs, input tax credits and distribution.
For transport companies, it influences freight invoicing, consignment documentation, interstate goods movement and working capital.
For small businesses, GST creates opportunities to participate in formal supply chains but also introduces compliance responsibilities.
The economic consequences are therefore complex.
GST has helped integrate India’s domestic market, but its benefits have not been distributed equally across every business, industry or household.
The most important question is no longer whether GST was a major reform.
It is whether the system is becoming simpler, fairer and more efficient as India approaches a decade of implementation.
This guide examines GST’s economic impact through 2026, including the important rate reforms announced in September 2025.
It also explains the consequences for road transportation, goods transport agencies, truck owners, freight brokers, manufacturers, consumers and the wider logistics industry.
📊 1. GST in India: Quick Facts for 2026
| GST Indicator | Information |
|---|---|
| Full form | Goods and Services Tax |
| Introduction date | 1 July 2017 |
| Type | Destination-based indirect tax |
| Main legislation | CGST, SGST, UTGST and IGST Acts |
| Policy institution | GST Council |
| Main standard rate after 2025 reform | 18% |
| Main merit rate | 5% |
| Special demerit rate | 40% for specified supplies |
| Other treatments | Nil rates, exemptions and special provisions |
| FY 2025–26 gross GST collection | Approximately ₹22.27 lakh crore |
| Registered GST taxpayers, May 2026 | Approximately 1.65 crore |
| Important logistics mechanism | E-way bill |
| Major business benefit | Input tax credit, where eligible |
| Major continuing challenge | Compliance complexity for some businesses |
The 56th GST Council meeting in September 2025 recommended a simplified rate structure centred on 5% and 18%, with a special 40% rate for selected supplies.
The reform also included significant changes affecting goods transportation, vehicles, consumer products and other industries.
Source: GST Council and Ministry of Finance publications.
🧾 2. What Is GST and How Does It Work?
GST is an indirect tax generally imposed on the supply of taxable goods and services.
Businesses collect GST on taxable supplies and remit the applicable amount to the government.
Eligible businesses can claim input tax credit for GST paid on qualifying purchases.
This mechanism is intended to reduce repeated taxation across the supply chain.
🧮 Simple GST Calculation
Suppose a manufacturer sells a taxable product for ₹10,000 before GST.
Assume the applicable GST rate is 18%.
| Particulars | Amount |
|---|---|
| Product value | ₹10,000 |
| GST at 18% | ₹1,800 |
| Invoice total | ₹11,800 |
The business must account for the tax according to applicable GST rules.
If it has eligible input tax credit, the amount payable in cash may be reduced.
📌 Why Input Tax Credit Matters
Consider a simplified example.
A business purchases qualifying inputs worth ₹5,000 plus ₹900 GST.
It subsequently sells a product for ₹10,000 plus ₹1,800 GST.
Assuming the full ₹900 credit is eligible and available:
Output GST: ₹1,800.
Eligible input tax credit: ₹900.
Net GST liability before considering other adjustments: ₹900.
This illustrates how GST can reduce cascading taxation.
Actual eligibility depends on statutory conditions, documentation, restrictions and compliance requirements.
🏛️ 3. India’s Tax System Before GST: Why Reform Was Necessary
Before GST, businesses encountered multiple indirect taxes administered at different levels of government.
These included central excise duty, service tax, state VAT, central sales tax and various other levies.
Different taxes had different rules and compliance procedures.
For businesses operating across multiple states, this created administrative complexity.
🚛 The Transportation Problem Before GST
Interstate goods movement frequently involved tax-related documentation and checkpoints.
Transport operators had to manage varying requirements.
Some trucks experienced delays at state borders.
Businesses sometimes established warehouses partly to manage state-specific tax structures.
🏭 The Manufacturing Problem
Manufacturers could face restrictions on credit across different tax categories.
This contributed to cascading taxes in some transactions.
📦 The Warehousing Problem
Tax considerations could influence where businesses located warehouses.
A company might maintain several distribution facilities even when a more consolidated network would be operationally efficient.
📊 Before GST Versus After GST
| Business Area | Before GST | After GST |
|---|---|---|
| Indirect tax structure | Multiple overlapping taxes | More integrated framework |
| Interstate goods movement | State-specific tax complications | More standardised GST documentation |
| Input tax credit | Fragmented credit arrangements | Broader integrated credit mechanism |
| Warehouse planning | Tax structure influenced locations | Greater flexibility to optimise networks |
| Tax administration | Multiple systems | GST-based digital administration |
| Freight documentation | Varied tax procedures | E-way bill framework |
| Compliance | Multiple indirect tax obligations | Unified framework, but continuing complexity |
GST did not remove every transport restriction or business compliance requirement.
Toll charges, vehicle permits, road safety regulations and other legal obligations remain relevant.
📈 4. GST Collection Growth: What the Numbers Reveal About India’s Economy
GST collections have increased substantially since implementation.
Government data reported gross collections of approximately ₹7.4 lakh crore in FY 2017–18.
By FY 2025–26, gross GST collections reached approximately ₹22.27 lakh crore.
📊 GST Revenue Comparison
| Financial Year | Gross GST Collection |
|---|---|
| 2017–18 | Approximately ₹7.4 lakh crore |
| 2021–22 | Approximately ₹13.76 lakh crore |
| 2025–26 | Approximately ₹22.27 lakh crore |
The number of registered taxpayers also increased from approximately 66.5 lakh in 2017 to 1.65 crore by May 2026.
These developments indicate a substantial expansion of the GST system.
However, rising GST collections should not be interpreted as proof that every household or business has become wealthier.
Collections can increase because of inflation, higher transaction values, economic growth, changes in tax rates, improved compliance and expansion of the taxpayer base.
A meaningful assessment must examine these factors separately.
🌟 5. Positive Impact of GST on the Indian Economy
🏭 A More Integrated National Market
GST reduced several tax-related barriers between states.
Businesses can increasingly plan supply chains around customer demand, infrastructure and operating costs.
This supports the concept of a more integrated domestic market.
📦 Better Supply-Chain Planning
Manufacturers can evaluate warehouse locations based on transportation efficiency and customer service.
Tax considerations remain relevant, but the earlier structure of multiple state-level indirect taxes no longer operates in the same way.
💻 Digital Tax Administration
GST encouraged the use of electronic invoices, returns and transaction records.
This can improve transparency and financial recordkeeping.
📊 Greater Formalisation
Businesses participating in formal supply chains often require appropriate invoices and tax documentation.
GST has contributed to stronger incentives for formal recordkeeping.
🤝 Input Tax Credit
Eligible businesses can offset qualifying input taxes against output tax liabilities.
This reduces certain forms of cascading taxation.
🏗️ Investment and Business Planning
A more integrated indirect tax framework can make some aspects of long-term business planning easier.
However, investment decisions also depend on infrastructure, financing, regulation and market demand.
⚠️ 6. Negative Impact and Continuing Challenges of GST
GST has delivered structural benefits, but implementation has also created difficulties.
🧾 Compliance Burden
Small businesses may need professional accounting support to manage registration, invoicing, returns and reconciliation.
💰 Working Capital Pressure
Businesses may experience cash-flow difficulties when tax payments and customer receipts occur at different times.
Delayed refunds or disputed credits can increase pressure.
📱 Technology Dependence
Digital compliance requires reliable internet access, suitable software and basic technical knowledge.
⚖️ Classification Disputes
Determining the correct tax treatment can be complicated when products or services fall into specialised categories.
🏭 Unequal Business Capacity
Large companies often have dedicated tax departments.
Small transport operators may rely on external accountants.
This can create differences in compliance costs.
🚛 Transport Industry Complexity
Freight services may involve different GST treatments depending on the nature of the service, consignment notes, tax-payment arrangements and applicable exemptions.
The result is a system that is more integrated than its predecessor but not always simple to operate.
🚛 7. GST Impact on India’s Road Transportation Industry
Road freight transportation is essential to India’s economy.
Trucks connect factories, farms, ports, warehouses, construction sites and markets.
GST changed the tax environment in which these services operate.
🛣️ Interstate Freight Movement
The removal of many earlier state tax checkpoints helped reduce some administrative barriers to interstate movement.
However, GST did not eliminate every road checkpoint, inspection or documentation requirement.
📦 Freight Documentation
The e-way bill system introduced a more standardised digital mechanism for specified goods movements.
🏭 Warehouse Consolidation
Some companies gained greater flexibility to consolidate distribution facilities.
Others continued using regional warehouses because of delivery times, customer demand and inventory requirements.
💻 Digital Freight Operations
Transport businesses increasingly use digital invoicing, accounting and documentation.
💰 GST Compliance Costs
Small transporters may face additional administrative responsibilities.
The financial impact depends on the business model and applicable tax treatment.
🚚 8. GST on Goods Transport Agency Services: Updated 2026 Explanation
This is one of the most important sections for Indian transporters.
A Goods Transport Agency, commonly called a GTA, is generally a person or business that provides services in relation to the transportation of goods by road and issues a consignment note.
The distinction between GTA services and other road goods transportation is important for GST treatment.
📊 GTA GST Rate Structure After the 2025 Reform
| GTA Tax Arrangement | GST Treatment |
|---|---|
| GTA service at merit rate | 5%, without ITC, subject to applicable conditions |
| Eligible GTA option at standard rate | 18%, with ITC |
| Reverse charge arrangement | May apply to specified recipients and supplies |
| Ordinary road goods transport outside GTA/courier classification | Generally exempt under the relevant provisions |
| Specified exempt GTA services | Exemption may apply subject to conditions |
The September 2025 GST Council clarification confirmed that GTA transportation could continue at 5% without ITC, with an option for 18% with full ITC.
Important: The earlier 12% GTA option should not be presented as the current standard alternative after the relevant 2025 changes.
The exact treatment depends on applicable notifications, the supplier’s tax-payment option, recipient status and transaction facts.
📄 9. What Is a Consignment Note and Why Does It Matter?
A consignment note is an important document in goods transportation.
Its issuance is a key feature in determining whether a service qualifies as a GTA service.
A typical consignment note records details such as the consignor, consignee, goods, origin, destination and transportation arrangement.
🚛 Practical Example
A truck owner may provide a vehicle for transporting goods.
Another business may operate as a GTA by issuing consignment notes and arranging transportation.
The GST treatment can differ because the nature of the service differs.
However, the absence of a consignment note should not be used as an artificial device to disguise the actual transaction.
Businesses should classify services according to their legal substance and applicable rules.
🔄 10. Reverse Charge Mechanism (RCM) in Road Transportation
Under the reverse charge mechanism, the recipient pays GST instead of the supplier for specified transactions.
GTA services may fall under reverse charge depending on the circumstances.
🧮 Illustrative RCM Example
Suppose an eligible GTA service has a taxable value of ₹50,000.
Assume the applicable rate is 5% under reverse charge.
| Particulars | Amount |
|---|---|
| Freight value | ₹50,000 |
| GST at 5% | ₹2,500 |
| Total tax liability under the example | ₹2,500 |
The specified recipient accounts for the tax according to applicable rules.
Whether the recipient can claim ITC depends on its eligibility and the relevant conditions.
⚠️ Important Compliance Point
Not every payment to a truck owner automatically attracts GTA reverse charge.
The service must be classified correctly.
Vehicle hiring, GTA transportation, courier services and ordinary road goods transport may have different treatments.
Transport businesses should verify their specific arrangements before invoicing.
🚛 11. GST Impact on Truck Owners, Trailer Operators and Freight Brokers
India’s road freight industry includes businesses with very different operating models.
A single-truck owner may work differently from a large fleet operator.
A freight broker may arrange transportation without owning vehicles.
A GTA may issue consignment notes and undertake transportation responsibility.
A specialised heavy-haul contractor may provide a broader project logistics service.
📊 Business Model Comparison
| Business Type | Main Activity | GST Consideration |
|---|---|---|
| Individual truck owner | Provides goods transportation or vehicle services | Depends on actual service classification |
| GTA | Road goods transportation with consignment note | GTA provisions |
| Freight broker | Arranges transportation | Brokerage service classification |
| Fleet operator | Operates commercial vehicles | Contract and service classification |
| Trailer operator | Heavy cargo transportation | GTA or other applicable treatment |
| ODC contractor | Specialised project cargo movement | Scope and contract structure |
| Warehouse operator | Storage and related services | Applicable warehousing provisions |
| Courier company | Parcel and express services | Courier-specific tax treatment |
A transport broker should not assume that its commission receives the same tax treatment as freight transportation.
Similarly, an ODC contract may contain transportation, engineering, escort, handling or other components requiring careful classification.
📦 12. GST and E-Way Bills: How Digital Documentation Changed Freight Movement
An e-way bill is an electronic document required for specified movements of goods under GST rules.
Its purpose is to provide information about the goods being transported.
🚚 Information Commonly Involved
Relevant details may include the supplier, recipient, goods description, value, transportation details and vehicle information.
📱 Benefits of the E-Way Bill System
Digital documentation can improve standardisation and provide authorities with transaction information.
It can also reduce dependence on some earlier paper-based procedures.
⚠️ Operational Challenges
Incorrect details, technical problems and documentation errors can disrupt transportation.
Drivers may depend on dispatchers or office staff to correct mistakes.
🛣️ Practical Recommendation
Transport companies should verify documentation before dispatch.
The person responsible for generating or updating the e-way bill should be clearly identified.
Businesses should also understand the applicable validity, extension and exception rules.
🏭 13. GST Impact on Manufacturing and Industrial Growth
Manufacturing companies purchase raw materials, process goods and distribute finished products.
GST influences these activities through tax rates, input credits and documentation requirements.
🏗️ Procurement
Eligible input tax credits can affect the effective cost of taxable purchases.
📦 Inventory Management
Businesses may reconsider warehouse locations and inventory arrangements.
🚛 Distribution
Integrated tax procedures can support interstate distribution.
⚙️ Industrial Equipment
The tax treatment of machinery, components and services can affect capital investment decisions.
📊 Important Limitation
GST is only one factor influencing industrial growth.
Electricity costs, labour availability, infrastructure, financing, market demand and other regulations also matter.
🏪 14. GST Impact on MSMEs and Small Traders
Micro, small and medium enterprises form an important part of India’s economy.
GST can help them participate in formal supply chains.
But compliance costs can be significant for very small businesses.
🌟 Potential Benefits
Formal invoices can support business relationships.
Digital records may improve financial transparency.
Eligible businesses can use input tax credits.
⚠️ Potential Difficulties
Small enterprises may struggle with accounting software, return filing, reconciliation and tax classification.
💰 Working Capital
Tax payment schedules and delayed customer payments can affect liquidity.
🤝 What MSMEs Need
Simpler compliance, clear guidance, predictable rules and accessible professional assistance can improve outcomes.
🛒 15. GST Impact on Consumers and Household Expenses
GST influences the final prices of many goods and services.
A reduction in the applicable tax rate may reduce the tax component of a product’s price.
However, the final retail price also depends on production costs, competition, margins and market conditions.
📉 Example of a Rate Reduction
Consider a product with a pre-tax value of ₹1,000.
| Particulars | GST at 18% | GST at 5% |
|---|---|---|
| Base price | ₹1,000 | ₹1,000 |
| GST | ₹180 | ₹50 |
| Final price | ₹1,180 | ₹1,050 |
In this simplified example, the tax-inclusive price falls by ₹130.
This assumes the base price remains unchanged and the full rate reduction is passed on to the consumer.
Actual market outcomes may differ.
🚗 16. GST Impact on Cars, Trucks, Buses and Automotive Components
The 2025 GST reforms included changes affecting several vehicle categories.
The GST Council recommended reductions for specified vehicles and related products.
🚛 Important Automotive Changes
The announced reforms included reducing GST on buses, trucks and ambulances from 28% to 18%.
Small cars and motorcycles within specified categories also received rate reductions.
A uniform 18% rate was announced for auto parts covered by the relevant reform provisions.
🏭 Why This Matters
Lower tax rates can influence vehicle purchase costs.
Fleet operators may evaluate new vehicle purchases differently when the tax component changes.
However, the total cost of a commercial vehicle also depends on registration, insurance, financing, maintenance and operating expenses.
🚚 Freight Rates
A reduction in truck purchase tax does not automatically produce an equivalent reduction in freight charges.
Freight pricing depends on multiple costs and market conditions.
🏗️ 17. GST Impact on Construction, Cement and Infrastructure
Construction is a major consumer of industrial materials and freight transportation.
The 2025 reforms included a reduction in the GST rate on cement from 28% to 18%.
🧱 Why Cement Matters
Cement is used in housing, commercial buildings, roads and infrastructure projects.
Changes in its tax treatment may influence project input costs.
🚛 Transportation Connection
Construction projects require substantial movement of cement, steel, aggregates, equipment and machinery.
Changes in construction activity can affect demand for trucks and trailers.
⚠️ Important Distinction
A reduction in cement GST does not guarantee a corresponding reduction in total construction costs.
Labour, land, steel, transportation and financing costs remain important.
🌾 18. GST Impact on Agriculture and Rural India
Agriculture is closely connected with transportation, storage and distribution.
GST affects agricultural supply chains through the tax treatment of equipment, inputs and related services.
🚜 Agricultural Equipment
The September 2025 reforms reduced GST on specified agricultural machinery and equipment.
📦 Agricultural Freight
Certain transportation services involving specified agricultural products may qualify for exemptions.
🏪 Rural Businesses
Small traders and agricultural supply businesses may benefit from improved market integration.
However, compliance requirements and infrastructure limitations can create challenges.
💻 19. GST and Digital Transformation of Indian Business
GST has encouraged businesses to adopt digital financial systems.
📱 Electronic Invoicing
Applicable businesses must follow relevant e-invoicing requirements.
🧾 Return Filing
Electronic returns create standardised reporting obligations.
📊 Accounting Software
Businesses increasingly use digital accounting tools to manage invoices and tax records.
🔍 Transparency
Digital records can improve traceability.
However, technology does not eliminate fraud, errors or disputes.
Strong oversight and practical taxpayer support remain necessary.
🌍 20. GST and India’s International Trade
GST affects export-oriented businesses through its treatment of supplies, input credits and refunds.
🚢 Export Competitiveness
Appropriate tax treatment can help prevent domestic indirect taxes from becoming embedded in export prices.
📦 Logistics
Exporters depend on freight transportation, warehousing, customs clearance and port services.
💰 Refunds
Timely processing of eligible refunds can support exporter liquidity.
⚠️ Continuing Challenges
Documentation errors, classification disputes and delayed refunds may create difficulties.
GST is therefore relevant to export competitiveness, but it operates alongside customs rules, international demand and logistics costs.
🚆 21. GST Impact on Road, Rail, Air and Water Transportation
Different transport services can receive different GST treatment.
The classification depends on the service, supplier, route and applicable exemptions.
📊 Transportation GST Overview
| Transportation Service | General GST Consideration |
|---|---|
| Ordinary road goods transport outside GTA/courier category | Generally exempt under applicable provisions |
| GTA road freight | 5% without ITC or eligible 18% option with ITC |
| Container transportation by specified rail operators | 5% without ITC or 18% with ITC under applicable options |
| Multimodal goods transportation | Special 5% or 18% treatment depending on conditions |
| Air cargo | Classification and route-specific provisions |
| Water transportation | Service-specific rates and exemptions |
| Courier services | Distinct from ordinary GTA transportation |
| Passenger transportation | Mode- and service-specific treatment |
Tax warning: This table is a general educational summary, not a substitute for checking the current notification applicable to a specific invoice.
💸 22. GST and the Cost of Logistics in India
Logistics costs include far more than taxation.
They may include freight charges, fuel, tolls, warehousing, handling, insurance, inventory costs and administrative expenses.
🚛 How GST Can Improve Efficiency
A more integrated tax framework can reduce certain administrative barriers.
Warehouse networks may be optimised.
Digital documentation can improve transaction visibility.
⚠️ Why Logistics Costs May Remain High
Congestion, fuel prices, vehicle maintenance, empty return journeys and loading delays continue to affect costs.
📊 Cost Components
| Logistics Cost | GST’s Potential Influence |
|---|---|
| Freight charges | Service tax treatment and compliance |
| Warehousing | Input credits and service taxation |
| Inventory | Distribution network decisions |
| Fuel | Major petroleum products remain outside GST |
| Toll charges | Separate road-user charges |
| Vehicle purchases | Applicable vehicle GST rates |
| Repairs and parts | Input tax treatment and eligibility |
| Documentation | Digital compliance requirements |
GST can improve the tax environment without solving every operational problem.
🛢️ 23. Why Petrol and Diesel Remain Important to the GST Debate
Petrol and diesel are major operating expenses for road transport companies.
As of the period covered by this article, petrol and high-speed diesel remain outside the regular GST levy.
They continue to be subject to their applicable existing tax arrangements.
🚛 Why This Matters to Transporters
Fuel costs can represent a substantial portion of truck operating expenses.
Businesses may not receive GST input tax credit on diesel purchases under the ordinary GST credit framework.
⚖️ The Policy Debate
Supporters of bringing fuel under GST argue that it could improve tax integration.
Others raise concerns about government revenue, rate-setting and fiscal implications.
Any future change would require appropriate policy and legal decisions.
📌 Important Point
Bringing fuel under GST would not automatically guarantee cheaper diesel.
The final price would depend on the applicable tax structure and other charges.
🏢 24. GST Impact on Warehousing and Logistics Parks
Warehousing plays an essential role in inventory management and distribution.
Before GST, state-specific tax considerations influenced some warehouse location decisions.
GST made it easier for businesses to evaluate distribution networks from a broader operational perspective.
📦 Warehouse Consolidation
Some businesses may benefit from fewer, larger distribution centres.
Others require multiple regional facilities to meet delivery expectations.
🚛 Freight Implications
Warehouse location affects transport distance, delivery time and vehicle utilisation.
🏗️ Logistics Parks
Modern logistics parks can combine warehousing, freight handling and multimodal connections.
GST is one factor supporting integrated logistics planning.
🧮 25. Practical GST Examples for Indian Transport Businesses
🚚 Example 1: GTA Freight Under a 5% Arrangement
Assume taxable freight of ₹1,00,000.
At 5%, the GST amount is ₹5,000.
Who pays the tax and whether input credit is available depends on the applicable arrangement.
🚛 Example 2: GTA Freight Under an Eligible 18% Arrangement
Assume taxable freight of ₹1,00,000.
GST at 18% equals ₹18,000.
The applicable input credit provisions must be considered when evaluating the economic cost.
🏭 Example 3: Manufacturer’s Freight Expense
A manufacturer receives a freight invoice.
The accounting team must determine whether the supply falls under forward charge, reverse charge or an exemption.
The invoice alone should not be classified based merely on the vehicle used.
🧾 Example 4: Freight Brokerage
A broker arranges a truck for a manufacturer.
The brokerage service should be assessed separately from the underlying freight transportation.
The correct GST treatment depends on the contractual relationship and actual services supplied.
These examples are illustrative and assume the specified transactions are taxable.
🚨 26. Common GST Mistakes Made by Transporters
❌ Incorrect Service Classification
Treating every road transportation transaction as a GTA service can lead to incorrect tax treatment.
❌ Using Outdated GST Rates
The September 2025 reforms changed important service-rate options.
❌ Confusing Freight and Brokerage
Brokerage services may be taxed differently from freight transportation.
❌ Incorrect Reverse Charge Treatment
Businesses should verify whether RCM applies to the specific transaction.
❌ Incomplete Documentation
Missing or inconsistent records can create compliance difficulties.
❌ Assuming Every Expense Qualifies for ITC
Input tax credit depends on eligibility and statutory restrictions.
❌ Ignoring E-Way Bill Requirements
Specified goods movements require appropriate documentation.
❌ Relying on Old Internet Articles
Tax laws change.
Businesses should check current notifications and professional guidance.
📉 27. Has GST Increased or Reduced Inflation in India?
GST can influence prices through changes in indirect tax rates and business costs.
However, inflation is affected by many factors.
These include food prices, energy costs, monetary conditions, supply disruptions and demand.
📊 Possible GST Effects
A tax reduction may lower the tax component of a product’s price.
A tax increase may raise it.
Improved supply-chain efficiency may reduce some business costs over time.
But the overall inflation effect cannot be established simply by comparing GST collections.
⚖️ Balanced Assessment
GST has changed the structure of indirect taxation.
Its effects on consumer prices differ across products, periods and market conditions.
🏛️ 28. GST and Government Revenue: Benefits and Responsibilities
GST provides substantial revenue to governments.
This revenue contributes to public finances alongside other taxes and receipts.
📈 Revenue Growth
Gross GST collections reached approximately ₹22.27 lakh crore in FY 2025–26.
🧾 Compliance and Revenue
Improved reporting can support tax administration.
🏗️ Public Investment
Government revenue supports the broader fiscal capacity to fund public services and infrastructure.
However, GST revenue is not automatically earmarked for a particular road, hospital or project.
⚖️ Fiscal Balance
Tax policy must balance revenue needs, economic efficiency, compliance costs and fairness.
🔮 29. Future of GST in India: 2026–2030
India’s GST system will continue to evolve through legal amendments, administrative reforms and technological development.
Potential priorities include simpler compliance, faster refunds and clearer classification rules.
💻 Digital Administration
Automation may reduce some manual work.
🏪 MSME Support
Simpler procedures could help smaller businesses.
🚛 Transport Compliance
Clearer guidance on freight classification and tax-payment arrangements could reduce disputes.
📊 Better Data
Improved data quality can support policy analysis.
⚖️ Fairness
Future reforms should consider their effects on consumers, small businesses and different industries.
These are potential priorities, not predictions of specific future government decisions.
❓ 30. Frequently Asked Questions About GST in India
1. What is GST in India?
GST is a destination-based indirect tax generally levied on taxable supplies of goods and services.
2. When was GST introduced?
GST was introduced on 1 July 2017.
3. What is the main benefit of GST?
One major benefit is a more integrated indirect tax framework with input tax credit mechanisms.
4. Has GST benefited the Indian economy?
GST has supported tax integration, formalisation and digital administration, although its effects vary across sectors.
5. What are the disadvantages of GST?
Challenges include compliance costs, classification disputes, working capital pressure and technology requirements.
6. What are the main GST rates in 2026?
Following the 2025 reform, the main structure centres on 5% and 18%, with a special 40% rate and other applicable exemptions and treatments.
7. What is the GST rate on GTA transportation?
The September 2025 clarification provides for 5% without ITC or an eligible 18% option with ITC.
8. Is every truck transportation service taxable under GST?
No. The treatment depends on the service classification and applicable provisions.
9. What is a Goods Transport Agency?
A GTA generally provides road goods transportation services and issues a consignment note.
10. What is reverse charge in GST?
Reverse charge places the tax-payment obligation on the recipient for specified supplies.
11. Is freight brokerage the same as GTA transportation?
No. Brokerage and goods transportation are different services and may have different GST treatment.
12. What is an e-way bill?
It is an electronic document required for specified goods movements under GST rules.
13. Does GST apply to diesel?
High-speed diesel remains outside the regular GST levy under the framework discussed here.
14. Has GST reduced logistics costs?
GST has removed some tax-related inefficiencies, but total logistics costs depend on many operational factors.
15. How does GST affect small transporters?
It can create formal business opportunities while also introducing compliance responsibilities.
16. What is input tax credit?
ITC allows eligible taxpayers to offset qualifying input taxes against output tax liabilities.
17. Did GST reduce tax checkpoints?
GST helped remove many earlier state tax-related checkpoints, but other lawful inspections and controls remain.
18. How does GST affect warehousing?
It allows businesses greater flexibility to optimise distribution networks without the same earlier state-level indirect tax structure.
19. Did GST rates change in 2025?
Yes. The 56th GST Council meeting announced major rate rationalisation measures.
20. What is the future of GST in India?
Future improvements may focus on simpler compliance, digital administration, clearer rules and efficient refunds.
🇮🇳 31. Conclusion: Has GST Made India’s Economy Stronger?
GST has fundamentally changed India’s indirect tax system.
It has helped integrate the domestic market, expanded digital tax administration and supported more standardised business processes.
For manufacturers, it has changed procurement and distribution planning.
For consumers, it affects the tax component of many everyday purchases.
For small businesses, it creates both formalisation opportunities and compliance challenges.
For the road transportation industry, GST has influenced freight documentation, consignment notes, tax-payment arrangements and warehouse networks.
The September 2025 reforms demonstrate that GST remains an evolving system.
However, a successful tax reform must be evaluated by more than revenue collection.
It should also be judged by simplicity, fairness, compliance costs, business competitiveness and practical outcomes.
🚛 GST and ABCC India Project Cargo Corporation
ABCC India Project Cargo Corporation operates in India’s transportation, project cargo and logistics sector.
Freight transportation businesses must consider GST compliance alongside vehicle suitability, cargo planning, route restrictions and commercial contracts.
For specialised trailer transportation and over-dimensional cargo, clear documentation and coordination between consignors, transporters and service providers are important.
Responsible logistics planning can help businesses manage operational and compliance risks.
🌱 Final Message
GST has created a more integrated foundation for India’s indirect taxation system.
Its long-term success will depend on continued improvements that support consumers, small businesses, manufacturers and the transportation industry.
The real success of GST should be measured not only by how much tax India collects, but also by how efficiently, fairly and transparently its economy operates.
📚 32. Official GST Sources and Further Reading
For legal accuracy and periodic updates, readers should consult official publications.
GST Council: Official recommendations, meeting records and rate notifications.
Central Board of Indirect Taxes and Customs: GST legislation, circulars, notifications and guidance.
Ministry of Finance: GST collection statistics and economic reports.
GST Portal: Registration, returns and taxpayer services.
E-Way Bill System: Goods movement documentation and related procedures.
Tax rules and exemptions may change. Businesses should verify the applicable law and obtain professional advice for specific transactions.
🚀 33. Google Search and Discover SEO Recommendations
Primary keyword: GST Impact on Indian Economy
Secondary keyword: GST Impact on Transportation and Logistics Industry
Suggested SEO title: GST Impact on Indian Economy 2026: Benefits & Challenges
Suggested URL: Keep the existing URL.
Suggested article category: Indian Economy, GST, Transportation and Logistics.
Suggested internal links: Road Transportation in India, Truck Drivers in India, Transport and Logistics Problems, Goods Transport Agency, Warehousing and Industrial Freight.
Recommended structured data: Article or BlogPosting.
Editorial update policy: Review the article whenever the GST Council announces material changes affecting freight transportation or major economic sectors.
Important: No article can guarantee a first-page Google ranking. Original industry experience, accurate tax information, strong internal linking and clear explanations will make this guide more useful and competitive.